

AUD/USD vs. Silver (XAGUSD) Trading Comparison & Strategies
Evaluate specifications, win rates, drawdowns, and trading setups for AUD/USD and Silver (XAGUSD) side-by-side.
Building a Forex Expert Advisor is only the beginning. Before trusting an automated trading system with real capital, traders need to understand how it behaves across historical market conditions.
Backtesting allows traders and developers to evaluate an EA against historical data, identify weaknesses, compare settings, and understand potential drawdowns before moving toward live trading.
Backtesting is the process of running an Expert Advisor against historical market data to see how the trading rules would have behaved under previous market conditions.
Instead of waiting months to see how an automated strategy performs, developers can use historical price data to simulate thousands of trades and evaluate the behaviour of an EA.
A proper backtest can help reveal important characteristics such as profitability, maximum drawdown, losing streaks, trade frequency, average profit and loss, and the effect of different market conditions.
An EA can look impressive after a handful of profitable trades while still having serious weaknesses. Backtesting provides a larger sample that makes it easier to understand how the strategy behaves.
Backtesting can help determine whether the rules programmed into an EA produce the intended behaviour over a meaningful historical period.
Profit alone is not enough. Maximum drawdown, consecutive losses and exposure should be studied before considering live deployment.
Trends, ranges, high volatility, low volatility and major economic events can produce very different results. A robust EA should be evaluated across varied conditions.
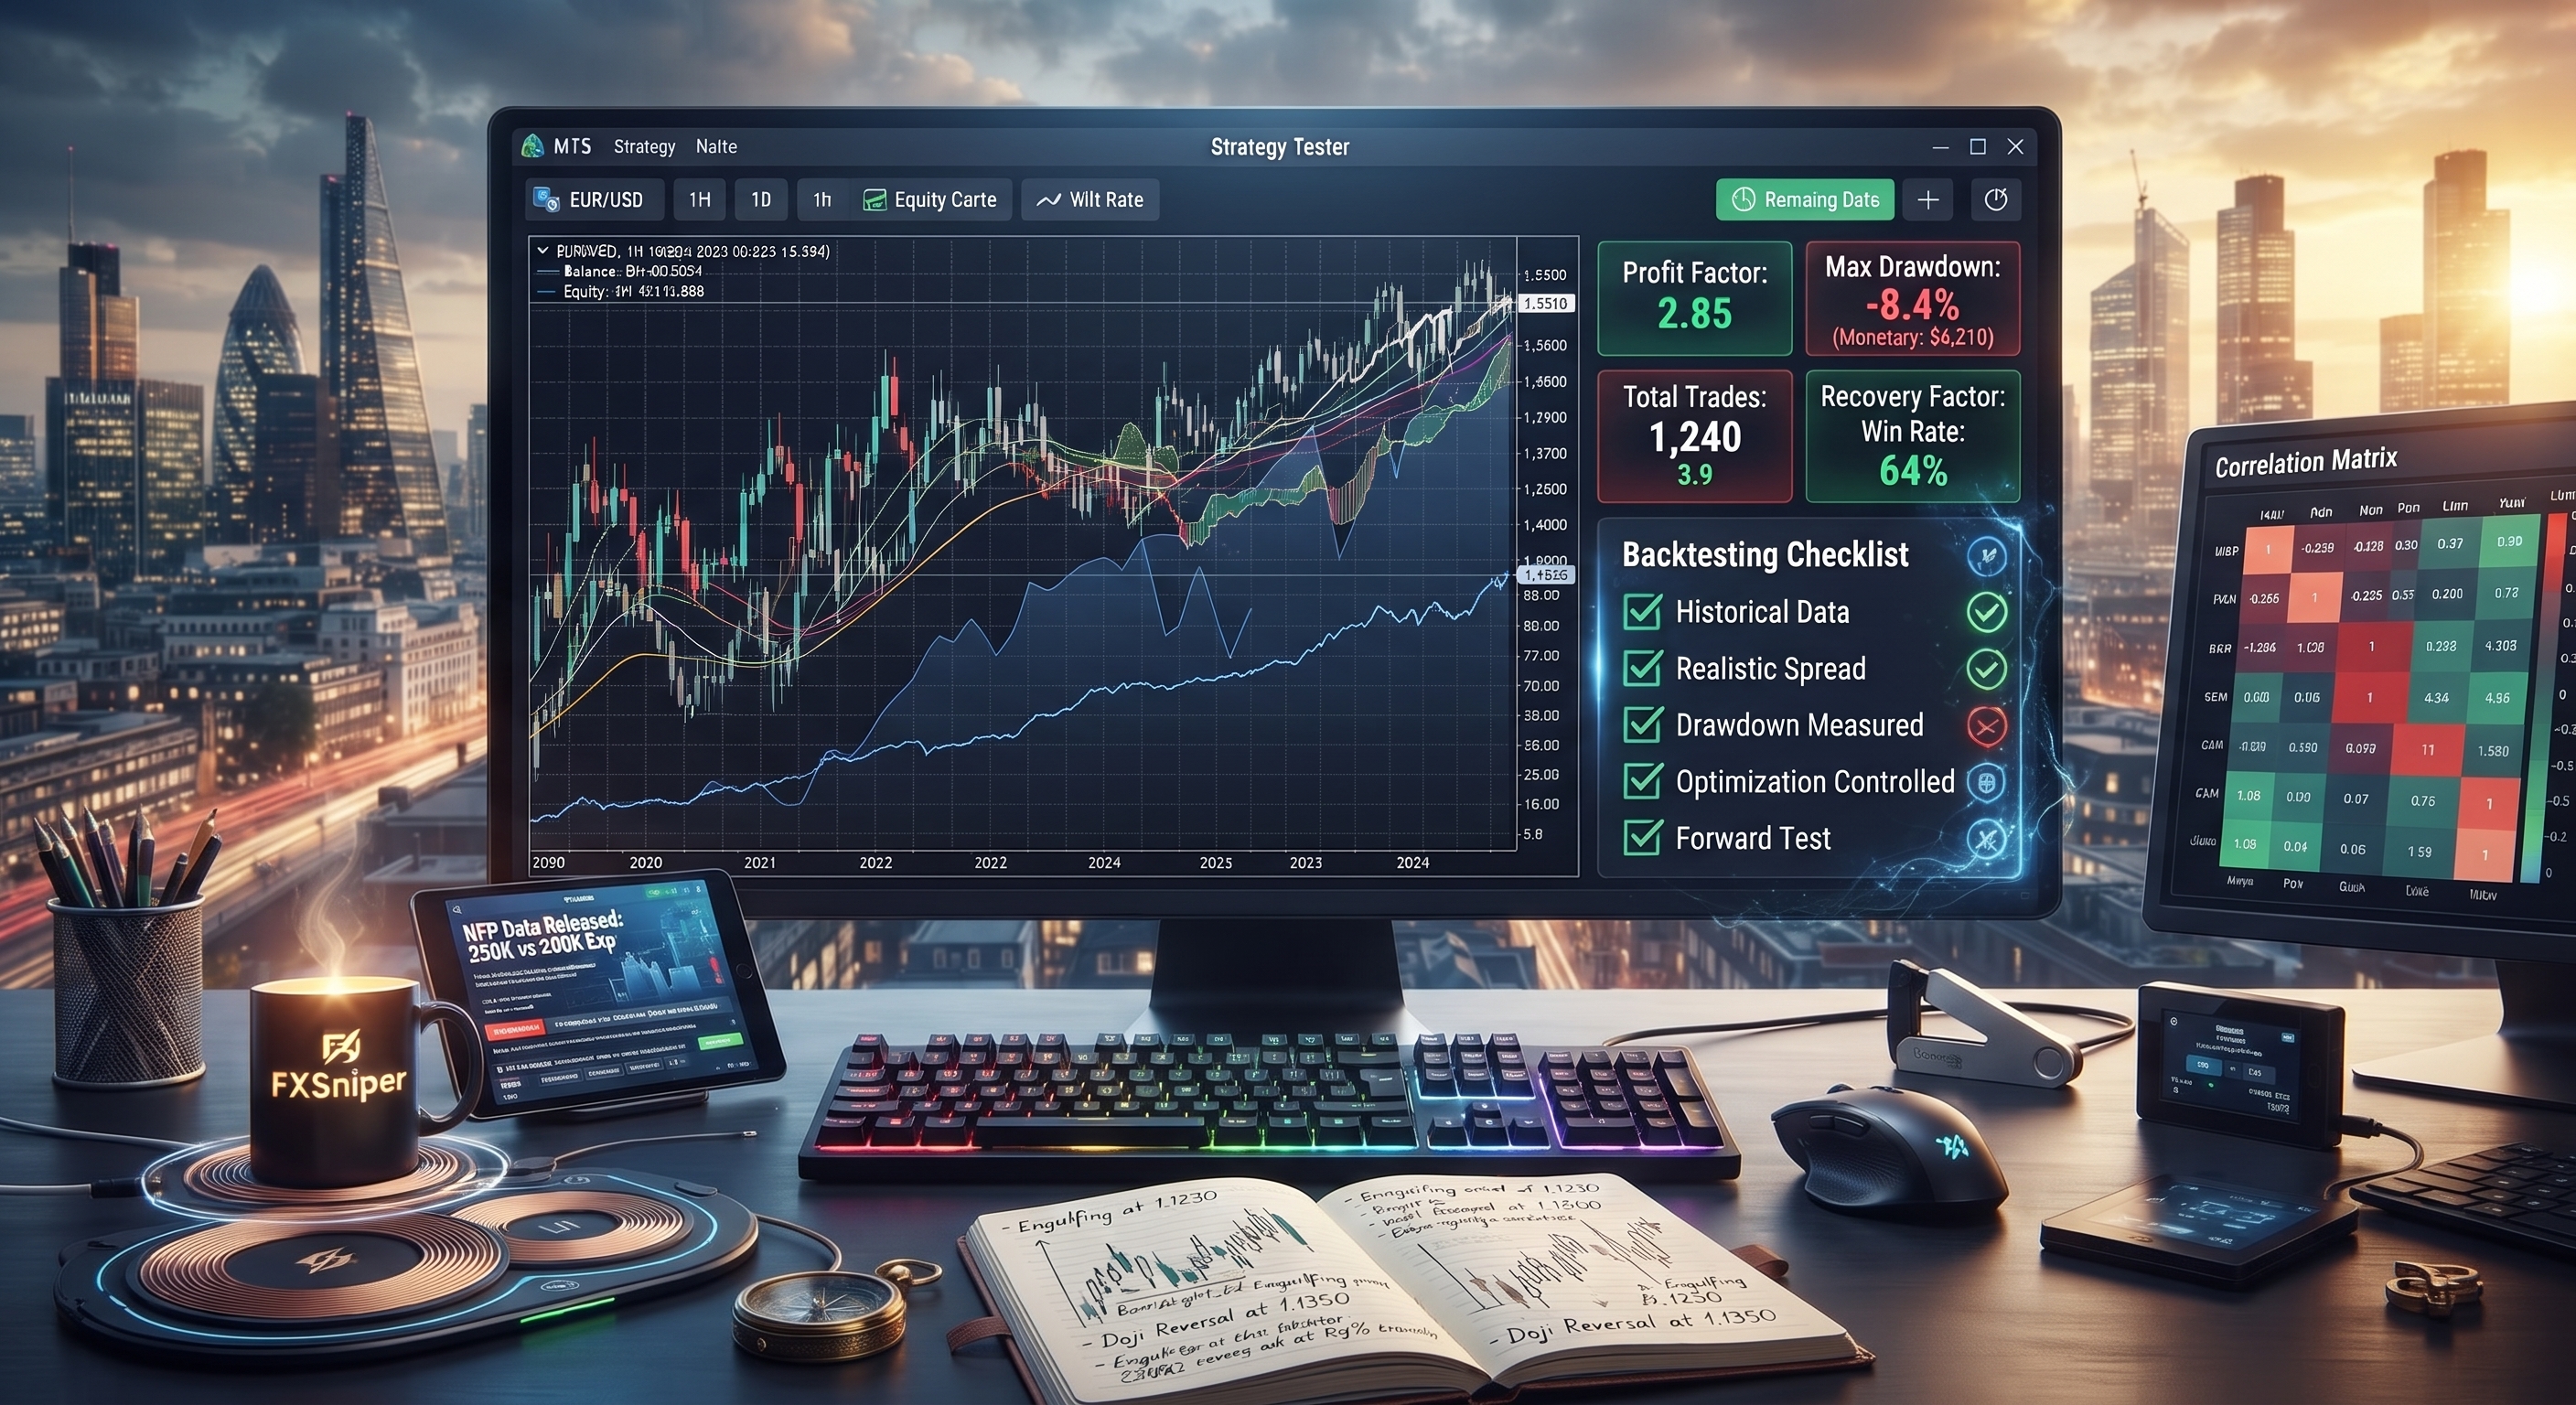
MetaTrader 5 includes the Strategy Tester, which allows traders and developers to test Expert Advisors using historical market data and different testing configurations.
Select the EA you want to test and confirm that the correct trading logic and parameters are loaded.
Choose the instrument that the EA was designed for. Gold, EURUSD, GBPUSD and other instruments can have very different volatility and execution characteristics.
Avoid judging a strategy using an extremely short historical period. A broader sample can provide a more useful picture of how the strategy behaves.
Consider spread, commissions, execution assumptions and other costs that may affect the results when the EA operates in a live environment.
A profitable backtest does not automatically mean that an EA is robust. Several metrics should be reviewed together.
Shows the overall result of the tested period after the simulated trading activity.
Shows how deeply the account declined from a previous equity peak.
Indicates the percentage of trades that closed profitably. Win rate should never be evaluated without considering average win and average loss.
Compares gross profits with gross losses and can help evaluate the overall efficiency of the strategy.
A strategy based on a very small number of trades may provide less statistical confidence than one tested across a larger sample.
Understanding losing streaks is important for determining whether the strategys risk settings are appropriate.
Optimization allows developers to test different parameter combinations and identify configurations that performed well during a historical period.
However, optimization can create a major problem known as overfitting. A strategy may become highly customized to historical data while performing poorly on new market data.
The goal of optimization should not be to find the perfect historical result. The goal should be to find reasonable parameters that remain stable across different data samples.
Backtesting uses historical information. Forward testing evaluates the EA using new market data after the strategy has been configured.
Useful for evaluating strategy behaviour across previous market conditions.
Helps determine whether the strategy continues to behave as expected outside the historical optimization sample.
Using both approaches can provide a more complete evaluation than relying on historical backtesting alone.
A strategy can look excellent during a short period and fail under different market conditions.
Maximum profit should not be the only optimization objective. Drawdown and stability matter too.
Spread, commission and slippage can materially affect short-term strategies.
Excessive optimization can produce historical results that do not generalize to future markets.
A successful backtest should be treated as one stage of evaluation, not as a guarantee of future performance.
Before evaluating an Expert Advisor, work through the following checklist.
Use sufficient historical data for the strategy being tested.
Consider spread, commission and execution assumptions.
Record maximum drawdown and recovery behaviour.
Determine how many consecutive losses occurred.
Avoid excessive parameter optimization.
Test the strategy using new market data.
Many trading strategies are shared through videos, tutorials and trading communities. A strategy becomes much easier to evaluate when its rules are clearly defined and converted into an automated system.
At FXSnipers, trading strategies can be studied, converted into MT5 Expert Advisors, tested against historical data and documented so traders can evaluate the implementation more objectively.
The purpose is not to guarantee future profits. The purpose is to make the trading rules measurable, testable and easier to evaluate.
Backtesting is one of the most important stages in developing and evaluating a Forex Expert Advisor.
A strong backtest does not guarantee that an EA will make money in the future. Markets change, execution conditions vary, and historical performance cannot predict future results with certainty.
Test → Measure → Validate → Forward Test
The objective is to understand how a trading system behaves, identify its weaknesses, control risk and avoid making decisions based only on attractive historical profit numbers.
A backtest is not a promise of future performance. It is a tool for understanding a trading system before putting capital at risk.
Test the strategy. Understand the risk. Validate the logic. Never confuse historical results with guaranteed future returns.
Algorithmic systems architect and quantitative developer at FXSnipers. Specializes in MQL5 strategy automation, MT5 tick data modeling, and mathematical risk management systems.
Automate your strategies with these fully backtested expert advisors matching this article's topics.
An "Attack and Defend" dual-brain system — Base Striker + Burst Sniper — driven by three independent price brains (pressure, momentum, direction), regime classification, and live USD Index confirmation, with daily profit locking and surplus protection.
This is a Martingale Expert Advisor with an additional three-brain that pairs a regime-aware Base entry engine with independent Burst and Chase recovery interventions, five-tier profit locking, and full news/volatility/session filtering.
A precision XAUUSD scalping EA that hunts liquidity sweeps of the Asian session range and strikes with trend-confirmed, risk-managed entries during London/New York hours.
The Rizwan Nawaz is a dedicated group of professional traders and quantitative developers. With years of experience building high-performance Expert Advisors, automated systems, and robust risk management strategies for MT4 and MT5, they share deep market insights to help retail traders automate their success.
Download the complete quantitative guide: Position Sizing Formulas, Prop Firm Drawdown Rules, and MQL5 Parameter Cheat Sheets.