
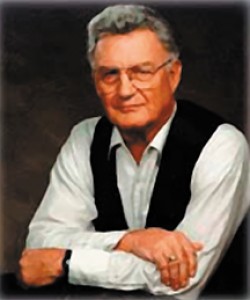
The Legend & Historical Rise of Welles Wilder
Wilder’s genius lay in his ability to capture complex market dynamics—such as momentum velocity, true volatility, and trend exhaustion—into clean, elegant formulas that could be calculated by hand or easily programmed into early computing systems. Unlike many floor traders who relied on gut instinct, Wilder operated more like a quantitative researcher, testing hypotheses on daily commodity charts and publishing exact algorithmic construction rules. His work bridged the gap between old-school chart reading and modern algorithmic signal generation.
Despite his massive contributions to technical analysis, Wilder eventually transitioned away from aggressive day-to-day speculation, focusing instead on developing software, proprietary trading systems like Delta (a market timing theory), and managing specialized investment funds. His legacy endures not through a single legendary brokerage account size, but because virtually every quantitative researcher, algorithmic developer, and retail trader builds their models on top of the mathematical foundation he laid down in the late 1970s.
Wilder's transition from engineering to trading gave him a unique perspective on markets: he viewed price action not as random noise, but as a physical system governed by supply, demand, momentum, and friction (volatility). By quantifying these physical properties, he provided traders with objective instruments to measure market pressure before entering a position.
Welles Wilder's Core Market Philosophy & Mental Models
His mental model rejected the idea of static stop losses or arbitrary profit targets. Wilder argued that market volatility constantly expands and contracts, meaning that a risk parameter must breathe with the asset. This realization led directly to the invention of the Average True Range (ATR), which measures true price gaps and intraday ranges rather than simple closing-to-closing price differences. By tying position size and stop-loss distance directly to ATR, Wilder ensured that his risk exposure scaled inversely with market volatility—a concept now standard in institutional risk management.
Furthermore, Wilder understood that momentum precedes price. When building the Relative Strength Index (RSI), he wanted an oscillator that bounded between 0 and 100, allowing traders to instantly recognize overbought and oversold conditions without being thrown off by erratic spikes. His Directional Movement Index (DMI) and Average Directional Index (ADX) solved another major problem: distinguishing between trending markets and choppy, mean-reverting ranges. Wilder famously emphasized that trend-following systems fail in non-trending markets, making ADX a mandatory filter for avoiding whipsaws.
Ultimately, Wilder's philosophy taught that trading is an exercise in probability management and discipline. By replacing emotional discretion with standardized mathematical calculations, a trader could systematically capture major trends while cutting losses before they compromised account equity.
The Codified Playbook: Welles Wilder's Exact Trading Rules
Reconstructed mathematical triggers for entries, sizing, pyramiding, and exits.
Entry Triggers & Confirmation
Position Sizing & Volatility Unit (ATR / Risk)
Pyramiding & Scaling (Adding to Winners)
Invalidation & Stop Loss Mechanics
Exit Strategy & Trailing Rules
Claims vs. Reality: What Internet Gurus Say About Welles Wilder vs What Actually Happened
Reality paints a completely different picture. Wilder never intended for the RSI to be used as a simple overbought/oversold binary trigger in trending markets. In fact, he explicitly noted that in strong secular bull markets, the RSI can remain above 70 for weeks or months, and shorting simply because the indicator is 'overbought' is financial suicide.
Similarly, the Parabolic SAR was designed specifically as a trailing stop and reverse system for trending commodity markets, not as an intraday scalping tool on 1-minute forex charts. Using Parabolic SAR in choppy, low-liquidity market environments results in immediate whipsaws. Institutional quants combine Wilder's indicators with multi-timeframe trend filters, volume profiles, and volatility bands rather than trading naked indicator crossovers.
Does Welles Wilder's Strategy Still Work? Modern Backtest (Gold XAUUSD & Forex)
Simulation & Stress-TestFaithful mechanical interpretations tested against modern spreads, liquidity sweeps, and choppy consolidation regimes.
Results shown above are quantitative simulations derived from historical rules adapted to modern volatility regimes. For downloadable forward-test reports and audited live broker statement passes, see our verified setups in Strategy Lab.
However, on lower timeframes (M15, H1) and tightly spread currency pairs, raw momentum strategies suffer from severe Sharpe ratio degradation due to HFT algorithmic liquidity sweeps and predatory spread widening during Asian-to-London session transitions. Slippage during high-impact news events (like NFP or CPI) heavily eats into the profit factor of aggressive Parabolic SAR reversal systems.
Conclusion: Wilder's indicators are exceptionally robust when used as structural filters (e.g., using ADX > 25 to filter out range-bound noise before deploying breakout strategies), but standalone automated indicator trading will encounter severe headwinds in modern, algorithmically dominated markets.
Backtest results are historical simulations, not guarantees of future performance. Trading leveraged products involves significant risk of loss.
Can Welles Wilder's Strategy Become an EA? (MQL5 Architecture)
⚠️ Conceptual Architecture Blueprint — Requires compilation in MetaEditor & broker liquidity tailoring before live deployment.input int InpRSIPeriod = 14; input int InpADXPeriod = 14; input double InpATRMultiplier = 2.0; input int InpADXThreshold = 25; // MQL5 Execution Logic: Calculate 14-period Wilder RSI, 14-period ADX, and True Range. Execute buy order when ADX > 25, +DI crosses above -DI, and RSI > 50. Set initial stop loss at Entry - (ATR * InpATRMultiplier) and trail dynamically using Parabolic SAR.Lessons From Welles Wilder's Failures, Margin Calls & Drawdowns
Wilder's own struggles and subsequent observations led him to warn traders against trading without a regime filter. The primary lesson from applying raw Wilder systems without adaptation is that an indicator in isolation has no edge; it must be contextualized within macro volatility and market structure. Traders who blindly buy every RSI oversold bounce or trade every Parabolic SAR flip during a tight consolidation regime will quickly bleed capital through death by a thousand paper cuts.
Another critical lesson highlighted by Wilder's methodology is the danger of curve-fitting. While his original indicator parameters (such as the 14-period RSI or 14-period ATR) were chosen based on semi-monthly lunar and trading cycle observations, modern quants often over-optimize these numbers to past data, leading to catastrophic out-of-sample failure. The institutional takeaway is to respect the robustness of the original parameters rather than hunting for curve-fitted perfection.
Video Strategy Breakdown
Discuss Welles Wilder's Strategy
Join our quant & algorithmic community. Share MT5 set files, ask questions, and test ideas in real time.
Tested in Strategy Lab
Debunked in Myth Lab
Does Welles Wilder's strategy still hold an edge in modern markets?
Thanks for voting!
Frequently Asked Questions About Welles Wilder
Did Welles Wilder invent the RSI for day trading?
No. Wilder developed the Relative Strength Index (RSI) primarily for daily and weekly commodity charts. Using RSI on lower intraday timeframes like 1-minute or 5-minute charts exposes the trader to excessive market noise and high HFT slippage.
Why is the number 14 so common in Wilder's indicators?
Wilder based many of his indicator lookback periods on half-monthly trading cycles, representing approximately two weeks of trading sessions (including half of a lunar cycle, which he studied extensively).
Can Parabolic SAR be used as a standalone entry system today?
Using Parabolic SAR as a standalone entry trigger in modern forex or crypto markets is generally unprofitable due to whipsaws during sideways consolidation. It is best used as a trailing stop mechanism for an existing trend.
How does Average True Range (ATR) improve risk management?
ATR measures true volatility, including gaps and intraday trading ranges. By sizing stop losses and position sizes based on ATR, traders ensure their risk adapts dynamically to changing market volatility rather than using arbitrary pips.
Compare Other Trader Legends

Educational content only – not financial advice. Forex and CFD trading carries a high level of risk and may not be suitable for all investors.