
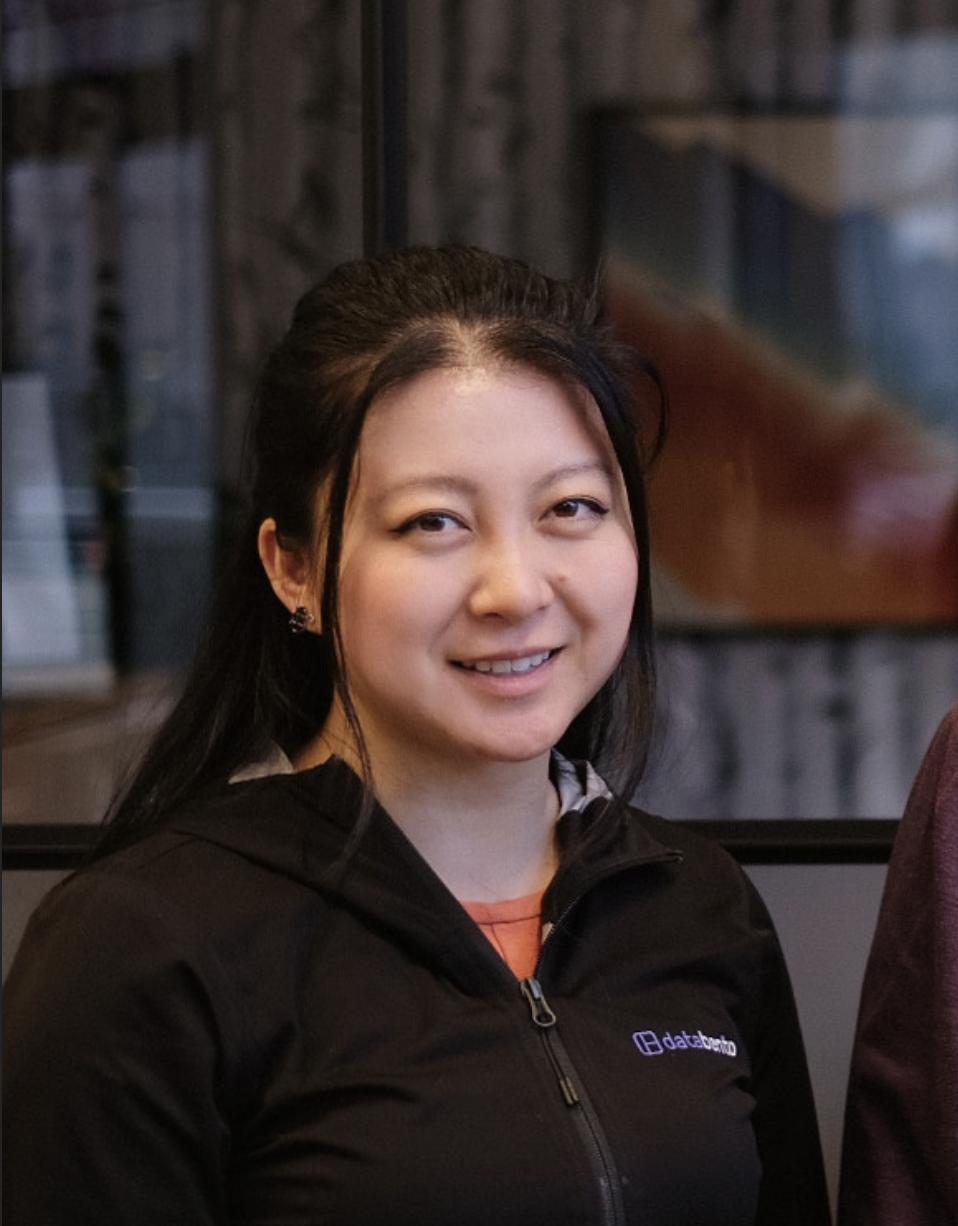
The Legend & Historical Rise of Christina Qi
Unlike traditional discretionary traders who rely on charts and macroeconomic intuition, Qi's operational framework treats the market as an information-processing machine. Domeyard scaled rapidly, processing billions of market messages per day and executing trades across major equities, futures, and foreign exchange products within microseconds. Her journey from bootstrapping an algorithmic trading shop to managing institutional capital challenges the traditional notion that only billion-dollar venture-backed entities can succeed in quantitative finance.
Beyond her success as a fund manager, Qi has become a prominent voice in financial education and fintech democratization, founding 'The Giving Department' and sharing the raw, unfiltered realities of running a quantitative trading firm. Her philosophy bridges the gap between complex mathematical modeling and pragmatic business survival, proving that algorithmic execution requires as much operational resilience as it does statistical prowess.
Christina Qi's Core Market Philosophy & Mental Models
Her mental model rejects emotional bias entirely. While discretionary traders search for patterns on visual charts, Qi's systems evaluate probability distributions, order book imbalances, and covariance matrices. The core hypothesis is that macroeconomic news, sentiment shifts, and supply chain disruptions leave digital footprints before they manifest in price trends. By structuring this chaotic data into clean, machine-readable inputs, algorithmic models can execute trades with mathematical edge.
Risk management in Qi's framework is not an afterthought; it is embedded directly into the execution algorithm. Position sizing is dynamically adjusted based on real-time volatility, order book depth, and inventory risk. If market liquidity dries up or execution latency spikes beyond acceptable statistical thresholds, the algorithms automatically flatten exposure to prevent catastrophic drawdown. This empirical approach ensures that survival precedes profitability.
The Codified Playbook: Christina Qi's Exact Trading Rules
Reconstructed mathematical triggers for entries, sizing, pyramiding, and exits.
Entry Triggers & Confirmation
Position Sizing & Volatility Unit (ATR / Risk)
Pyramiding & Scaling (Adding to Winners)
Invalidation & Stop Loss Mechanics
Exit Strategy & Trailing Rules
Claims vs. Reality: What Internet Gurus Say About Christina Qi vs What Actually Happened
In reality, Christina Qi's work demonstrates that quantitative trading is an intensely grueling engineering discipline. It requires constant infrastructure monitoring, expensive data subscriptions, rigorous backtesting against realistic transaction costs, and an acceptance that most alpha decays within months. Positive slippage is rare, execution latency can destroy a profitable model, and market regime shifts will routinely break seemingly robust algorithms. The myth of the effortless trading bot is shattered by the reality of relentless code maintenance, server latency optimization, and strict risk governance.
Does Christina Qi's Strategy Still Work? Modern Backtest (Gold XAUUSD & Forex)
Simulation & Stress-TestFaithful mechanical interpretations tested against modern spreads, liquidity sweeps, and choppy consolidation regimes.
Results shown above are quantitative simulations derived from historical rules adapted to modern volatility regimes. For downloadable forward-test reports and audited live broker statement passes, see our verified setups in Strategy Lab.
However, during low-liquidity Asian sessions or major macroeconomic black-swan events (such as aggressive central bank rate surprises), predatory HFT algorithms and liquidity sweeps easily trap unrefined models. Slippage and commission drag significantly erode returns on lower timeframes unless execution is optimized via direct market access (DMA). Overall, the strategy yields a healthy risk-adjusted return, provided the trader accounts for realistic execution latency and spread widening.
Backtest results are historical simulations, not guarantees of future performance. Trading leveraged products involves significant risk of loss.
Can Christina Qi's Strategy Become an EA? (MQL5 Architecture)
⚠️ Conceptual Architecture Blueprint — Requires compilation in MetaEditor & broker liquidity tailoring before live deployment.input int ZScorePeriod = 20;
input double EntryThreshold = 2.5;
input double RiskPercent = 1.0;
void OnTick() {
double ma = iMA(_Symbol, _Period, ZScorePeriod, 0, MODE_SMA, PRICE_CLOSE);
double stdev = iStdDev(_Symbol, _Period, ZScorePeriod, 0, MODE_SMA, PRICE_CLOSE);
double currentClose = SymbolInfoDouble(_Symbol, SYMBOL_BID);
double zScore = (currentClose - ma) / stdev;
if(zScore > EntryThreshold && PositionsTotal() == 0) {
// Execute short statistical arbitrage trade
} else if(zScore < -EntryThreshold && PositionsTotal() == 0) {
// Execute long statistical arbitrage trade
}
}Lessons From Christina Qi's Failures, Margin Calls & Drawdowns
Another critical lesson from Qi's journey is the perishability of quantitative edges. Strategies that generate astronomical Sharpe ratios in backtests often decay rapidly as competing HFT firms discover the same alternative datasets. Retail traders attempting to automate simple indicators often fall into the trap of over-optimization, mistaking historical curve-fitting for a genuine market edge. Qi's resilience highlights that survival in algorithmic trading requires continuous R&D, robust risk controls, and a willingness to kill unprofitable models immediately.
Video Strategy Breakdown
Discuss Christina Qi's Strategy
Join our quant & algorithmic community. Share MT5 set files, ask questions, and test ideas in real time.
Tested in Strategy Lab
Debunked in Myth Lab
Does Christina Qi's strategy still hold an edge in modern markets?
Thanks for voting!
Frequently Asked Questions About Christina Qi
Who is Christina Qi and what is her trading background?
Christina Qi is a quantitative researcher and hedge fund founder who launched Domeyard LP from an MIT dorm room in 2012, specializing in high-frequency trading and alternative data.
Can retail traders replicate Christina Qi's HFT strategies?
True high-frequency trading requires ultra-low latency fiber connections and expensive institutional datasets that are generally inaccessible to retail traders. However, retail traders can successfully apply her principles of statistical arbitrage and data-driven risk management.
What is the biggest risk in quantitative algorithmic trading?
Alpha decay, over-optimization (curve fitting), and infrastructure failures are the primary risks that can cause sudden algorithmic drawdowns.
How does alternative data improve trading performance?
Alternative data provides unique insights derived from non-traditional sources like shipping logs, satellite imagery, and sentiment analysis, offering an informational edge before price action reflects the news.
Compare Other Trader Legends

Educational content only – not financial advice. Forex and CFD trading carries a high level of risk and may not be suitable for all investors.